Fantasising about watching the sunrise as it reflects the dunes of the desert, shopping at the souk in the afternoon, and taking a relaxing break at the waterfront beaches in the evening? Your dreams can come true even if you are not a UAE citizen. An expat can easily buy, sell and rent properties across the United Arab Emirates.
But if you are wondering how to invest in a property, which emirate is best to invest in, and what the procedure looks like? We have prepared a comprehensive guide for you with all the information you may need to buy property in the UAE as a foreign investor. This UAE Property Buying Guide covers everything from the UAE property buying process for expats to the documents required to buy property in the UAE.
Can Foreigners Buy Property in the UAE?
Yes, you do not need UAE citizenship to buy properties. Foreign investors in the UAE can easily buy, rent, sell and pass down real estate using a valid passport. In fact, buying property in the UAE is one of the primary pathways of securing residency.
Foreign investors can simply buy properties in free zones designated by each emirate's government. An investment of AED 2,000,000 or $545,000 USD can get you a 10-year- golden visa. When it comes to properties bought on mortgage, they qualify as property investments if AED 2 million of the property’s equity value has been paid off.
Freehold vs Leasehold Properties: What's the Difference?
First, let’s try to understand what the terms Freehold properties and Leasehold properties mean.
Freehold property UAE refers to real estate properties that are owned by you along with the land that they sit on in perpetuity or forever. On the other hand, leasehold properties are the ones that are owned by someone else for a particular number of years, such as 30 years or 99 years, but the underlying land or the land that it has been built on belongs to the landlord or owner. The two-carry various other differences based on multiple parameters; let’s try to understand them one by one with the help of the following table.
|
Feature |
Freehold |
Leasehold |
|
Land Ownership |
Own both the structure and the land that it has been built on. |
The freeholder or the original landlord owns the land. |
|
Duration |
Forever |
For the agreed upon duration (generally 99 years; can be renewed as per the agreement) |
|
Control and Changes |
Full control to restructure, remodel, or conduct any structural altercations. |
Requires approval from the landlord or landowner. |
|
Ongoing Land Costs |
No rent. |
Requires maintenance fees, ground rent or lease amount as per the agreement. |
|
Inheritance and Resale |
Can be easily passed to heirs or sell without any third-party approval. |
Transfer or inheritance depends on remaining lease duration or renewal terms. |
|
Property Value |
The value appreciates depending on the market and increase as per trends. |
Value may depreciate as the remaining term on the lease gets shorter. |
Step-by-Step Process to Buy Property in the UAE
Buying a property in the UAE is an easy process and may take 2 to 4 weeks to be completed. Foreign investors can buy properties in both the primary market and the secondary market. This step-by-step guide to buying property in the UAE explains the process in simple terms.
In the primary market, buyers buy directly from developers, while in the secondary market, you buy from an existing owner or investor rather than the developer. Also, in the UAE, you can buy both land properties that are still under construction and ready properties, whose construction is completed and the keys can be handed to the buyer.
Now, when you are assured that you can buy a property across the UAE, let’s get to know the procedure of how you can buy a piece of real estate within four easy steps.
Step 1: Establish budget and secure Mortgage pre-approval.
This step will help you take a mindful decision before you sign the contract. Set your budget and add 7%-8% in purchasing fees on top of the property price. As a foreign investor, you have to pay at least 20% to 25% as a down payment in cash for properties.
If you are financing, you will need an Approval in Principle from a UAE bank to confirm the maximum borrowing limit.
Step 2: Sign the Memorandum of Understanding (MoU)
This is the binding agreement between the buyer and the seller. In this agreement, payment schedules and completion dates are mentioned. Signing this document means both parties agree to it. The buyer has to submit a 10% security deposit cheque held by the real estate brokerage until transfer.
Step 3: Obtain Developer NOC or No Objection Certificate.
To ensure no fees like service charges, utilities and municipal fees are pending on the seller side. NOC issuance takes 3 to 7 business days. It also requires an issuance fee of around AED 500 to AED 5,000.
Step 4: Property transfer at DLD/ Registration Trustee Office.
It is the final step when final legal transfer and title deed issuance take place. The buyer, seller and real estate agent attend an authorised Property Registration Trustee Office or land department. The buyer makes the final payment along with a 4% land department transfer fee and trust admin fees via a cheque or verified bank transfer.
Finally, the DLD conducts the ownership transfer and generates the Digital Title Deed.
Legal Requirements and Documents for Foreign Buyers
Since you know now that it takes a few weeks to buy a property in the UAE, allow us to help you enlist the documents required to buy property in the UAE so that the buying process remains seamless and quick.
1. Primary Identification and KYC documents
Let’s try to get over the basics first; these documents are simply proof of your identity, especially when you are buying as a foreign citizen. Keep the following close:
• Valid Passport – It must have at least six months of validity remaining.
• Proof of Address – Your current proof of address can be proven by a recent utility bill, bank statement, or official address document from the home country or UAE residence if you are a citizen.
• Emirates ID and Residence Visa – For Emirates citizens, these documents are required alongside the passport.
• Proof of Income/ Bank Statements – At least 3 to 6 months of stamped bank statements to prove a source of income to satisfy AML regulations.
2. Core Legal Contracts and Ownership Documents
Since buying a property is an agreement between two parties, the following proof of documents is required.
• Sales and Purchase Agreement (SPA)/ Form F
It is issued by a Real Estate Broker/ Developer for the purpose of showing proof of a binding contract with the mention of purchase price, payment schedules and handover conditions.
• No Objection Certificate (NOC)
This will be given by the master developer and confirms the property has no outstanding service charge liabilities or debts.
• Oqood (Interim Registration)
Issued by the Land Department, e.g. DLD, for the purpose of your initial ownership rights for off-plan properties during construction.
• Title Deed
It is given by the land department and is the proof of full ownership issued at property transfer or completion.
3. Buying via a Foreign Company or Corporate Entity
If you don’t want to buy the property under your name and instead intend to do the purchase under a company or corporate entity, a set of documentation is required to prove that the company or entity is genuine. The following documents will suffice.
• Certificate of Incorporation/ Trade License
It is the company’s business registration proof.
• Memorandum and Articles of Association (MOA/ AOA)
To prove the company’s legal structure and power to verify that it’s been run legally.
• Board Resolution
It is proof that the company’s directors and everyone who has the POA agree to this purchase.
• Incumbency Certificate
It is the documentation of who owns the company and other people who have the power. It is basically asked for Anti-Money Laundering checks.
4. Special Scenarios
• If buying remotely via Power of Attorney (PoA)
The PoA documents should be notarised legally in the home country, authenticated by the Ministry of Foreign Affairs, also get them attested by the UAE embassy in the home country and lastly, get them translated into Arabic, if required.
• If financing via a UAE Mortgage
Show the documents such as proof of income, salary certificate, company financial statements, tax returns along with a mortgage pre-approval letter.
Costs Involved in Purchasing Property in the UAE
Apart from the fees mentioned above, there are other costs incurred in the process that you must be aware of. We have listed them one by one below.
1. Upfront Government and Administrative Fees
Under this category, the following fees are observed
• Land Department Transfer Fee, i.e. 4% of the purchase price.
• Title Deed/Admin Issuance Fee i.e. AED 580 to AED 1,000.
• Trustee Registration Fee i.e. AED 4,000 + 5% VAT
• Developed No Objection Certificate (NOC) i.e. AED 500 to AED 5,000 + VAT
2. Professional and Agency Fees
These fees include the broker’s fees or agency fees that help you land the property or be there through the purchasing process.
• Real Estate Agent Commission i.e. 2% of the purchase price + % VAT
• Conveyancing/ Legal Fees (optional) i.e. AED 6000 to AED 12,000
3. Mortgage Financing Costs
If you are not paying directly and require a loan or mortgage, the following additional fees will be required.
• Mortgage Registration Fee:
0.25% of the total loan amount, along with AED 290.
• Bank Processing/ Arrangement Fee:
0.5% to 1% of the loan amount + 5% VAT
• Property Valuation Fee:
AED 2,500 to AED 3,500 + 5% VAT
Mandatory Insurance includes:
• Property Insurance: approximately AED 1,000/ year
• Mortgage Life Insurance: approximately 0.3% to 0.6% annually on the remaining loan balance.
4. Ongoing and Post- Handover Utility Costs
Once the purchase and handover are done, operational costs are incurred.
• Utility Connection Deposits incurred by DEWA/ FEWA/ AADC: approximately AED 2,000 for apartments and AED 4,000 for villas. These are refundable deposits.
• District Cooling Deposits incurred by Empower/ Tabreed: approximately AED 2,000 to AED 4,000 refundable deposits for properties with a central cooling system.
• Annual Service Charges/ HOA Maintenance: ranges approximately between AED 10 to AED 30+ per sq. ft. per year. It varies from building, luxury amenities and location. An upfront fee for 6 to 12 months is paid to the developers in advance.
Best Cities for Property Investment: Dubai, Ras Al Khaimah & Abu Dhabi
The above-mentioned cities are the three strongest real estate markets now. But each has its own speciality and attributes to offer to you. Let’s explore them step by step so that you can align them with your property investment UAE objectives and understand the best places to buy property in the UAE for investment.
Dubai
Considering its popularity, Dubai remains an attractive destination for real estate aficionados. It is considered best for investors who prioritise liquidity and plan to have holiday home rental yields and understand the properties that have historical resale value.
Dubai offers a high demand for rental properties around areas like Marina, Downtown, and Palm Jumeirah. They also have flexible payment plans in both the primary and secondary market. Global presence also makes it easier to buy and sell properties. However, this popularity results in high purchase prices as well.
Abu Dhabi
This destination is perfect for investors who are looking for long-term, steady growth. The market offers sovereign expansion and cultural developments that attract those who love capital preservation, low volatility and long-term, high-income family tenants.
Abu Dhabi offers low government registration fees and strong capital appreciation in areas like Yas Island, including entertainment and theme parks and Saadiyat Island at Louvre Abu Dhabi and Guggenheim.
Ras Al Khaimah
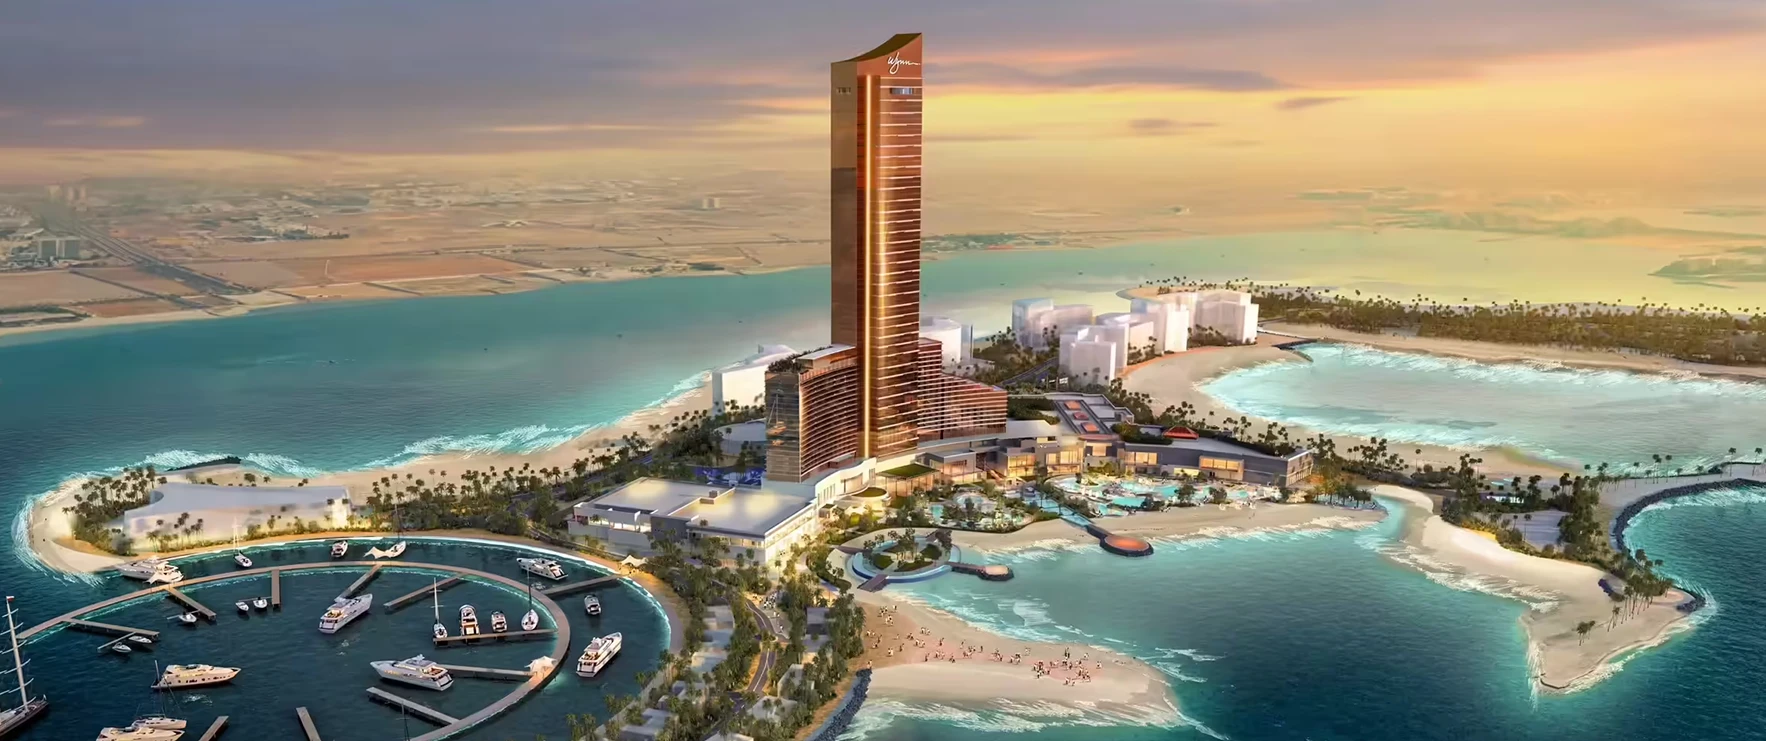
This real estate destination is for the most ambitious ones. With the upcoming arrival of the Wynn Al Marjan Island, this emirate has been attracting more real estate enthusiasts than any other emirate.
Promising waterfront apartments, holiday homes, and family residences on Al Marjan Island, Mina Al Arab and Al Hamra, this destination offers a haven away from the hustle and bustle of the world. A casino for entertainment, lower per-square-foot purchase prices than Dubai and Abu Dhabi, as well as high short-term rental ROI prospective yields to reach around 8% to 10%.
Choose Ras Al Khaimah if you want to enter a rapidly growing market at a lower price and capitalise on the resort and entertainment tourism boom at Al Marjan Island.
Invest with Mantra Properties to explore opportunities across the UAE real estate market and explore luxury properties in the UAE for your next investment.